
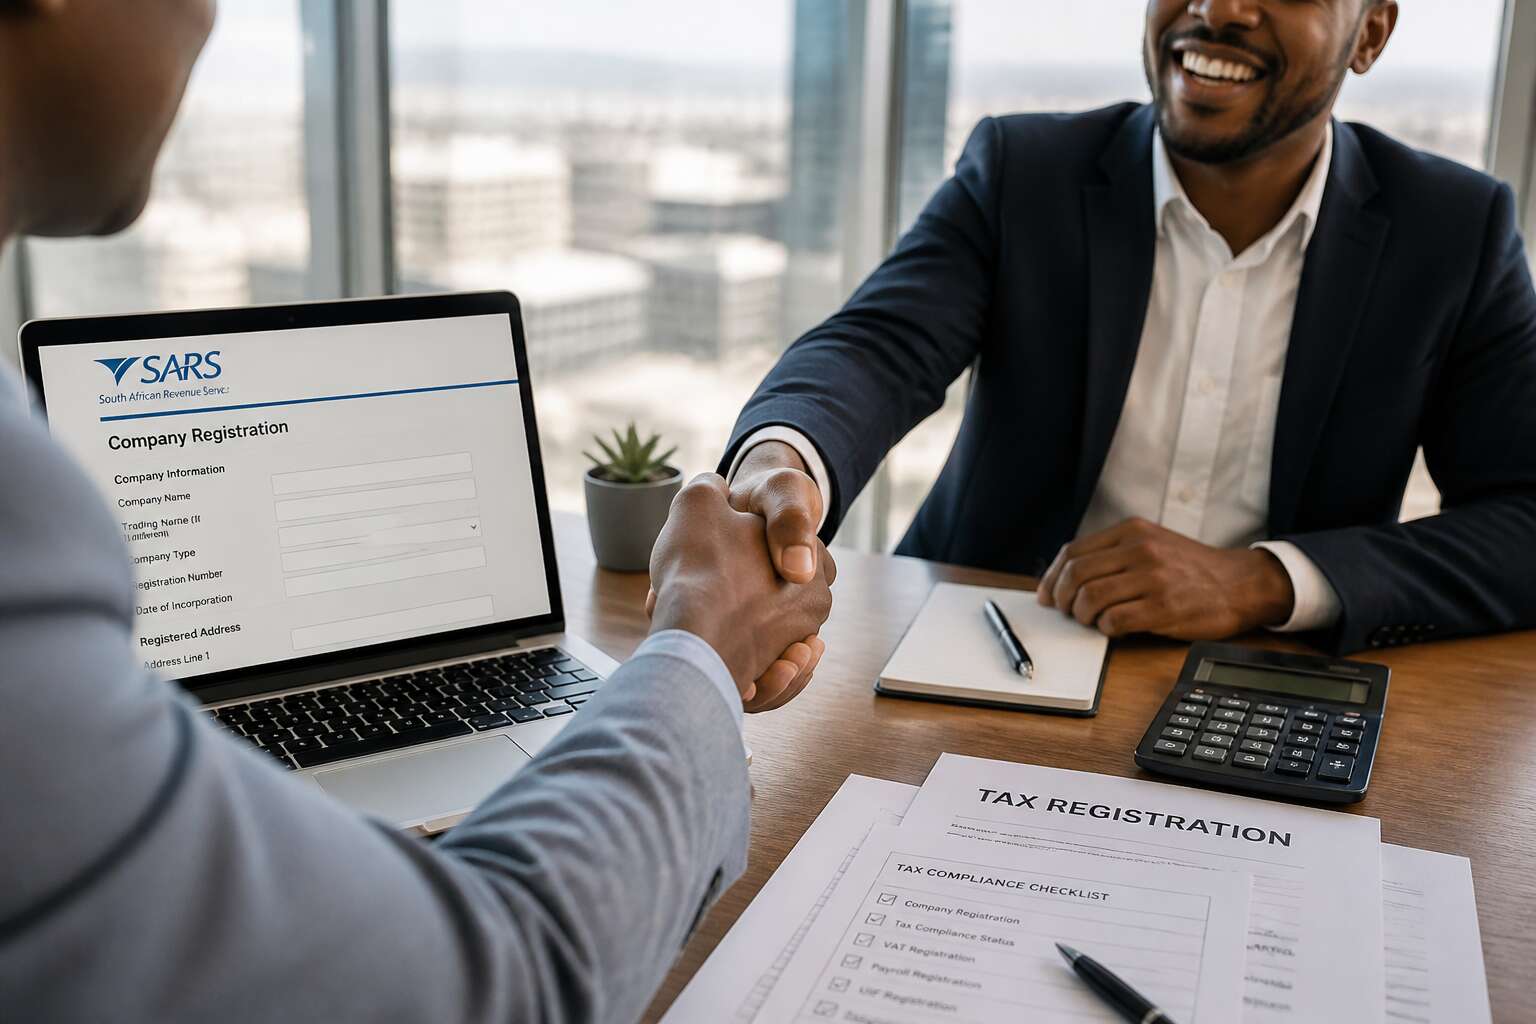
Understanding SARS Registration for Companies
Why SARS Registration is Mandatory
In South Africa, the CIPC approves roughly 20,000 company registrations each month. The statutory process, however, only begins once that certificate lands. Your company registration SARS process is a separate and non-negotiable introduction to the tax collector, one that many founders treat as optional paperwork. It is not.
The Companies Act requires every active entity to register as a taxpayer, and SARS enforces this with punctuality. I have watched clever founders trip in this exact spot. The bank would not open an account without a tax number, and the receiver can hold directors personally liable for company debts when this obligation is ignored. Company registration SARS approval gives your business the legal capacity to trade, hire, and invoice without fear of personal exposure. Without it, that pristine certificate is merely a decorative document with an unfortunate habit of attracting penalties. Elegance, in business, is a matter of compliance.
Who Needs to Register
Every entity that holds a CIPC registration file also holds an obligation with SARS. The categories are broader than directors assume:
- Private and public companies, regardless of size
- Personal liability companies and non-profit companies
- External companies with a physical presence in South Africa
- Branches of foreign corporations conducting local business
The company registration SARS process begins with that list, not after your first invoice. I have seen directors of dormant shelf companies assume silence protects them. It does not. SARS maintains its own register, and the two databases reconcile. If CIPC knows you exist, SARS will eventually find out as well.
Foreign ownership does not change this. The company registration SARS requirements apply to an external company before it hires a single local employee or signs a single lease. SARS judges existence, not activity. A company that registers with CIPC and then waits for revenue still lands on the tax roll within weeks.
The Legal Framework
The legal skeleton here is thinner than people assume. The Income Tax Act, No. 58 of 1962, and the Tax Administration Act, No. 28 of 2011, form the core. The latter gives SARS the authority to compel registration. It does not wait for a company to volunteer. The Tax Administration Act defines a “registered taxpayer” broadly, and the net catches every CIPC entry, no matter how small.
This means compliance starts with a statutory duty, not a choice. The registration itself is triggered by the mere existence of a legal persona. SARS does not ask permission. It simply expects the formalities to be completed, and it tracks the process through the two databases reconciling behind the scenes.
The framework also outlines what happens after the company registration SARS link is established:
1. The company files its first return within the prescribed period.
2. SARS assigns a tax reference number, not a courtesy, but a legal identifier.
3. The obligation remains even during periods of zero activity.
Each step carries consequences if ignored. The Act does not require a company to earn income first. It requires registration first. That sequence is fixed, and the administrative penalties are tied to the calendar from the moment CIPC issues the registration number. Silence is never a defence in this framework.
Preparing for Company Registration with SARS
Required Documents
Gathering the paperwork for company registration sars demands more patience than most entrepreneurs expect. Missing one document stalls the entire process.
Your ID, proof of physical address, and completed forms form the foundation. Alongside these, you need:
- A certified copy of your ID
- Proof of business address
- Company registration certificate from CIPC
- Bank account confirmation letter
Each document must be certified within three months. SARS officers reject stale certifications without hesitation, so check dates before you queue. You will visit a branch or work through eFiling, depending on your preference. Both routes require the same paperwork, and neither forgives an incomplete folder. The entire experience tests your organisational skills rather than your business savvy.
Choosing the Right Tax Type
One of the most consequential decisions during company registration sars involves selecting the correct tax type. Get this wrong, and you face penalties or missed deductions. A sole proprietor may only need provisional tax, while a private company must register for income tax, and possibly VAT if annual turnover exceeds R1 million. PAYE becomes mandatory once you hire employees.
Your choice affects how often you file and what records you keep. SARS allows you to register for multiple taxes under one profile, but each carries separate obligations. Consider these factors:
- Your legal structure
- Expected annual turnover
- Whether you will employ staff
- Goods or services subject to VAT
The selected tax type determines your filing frequency, record keeping standards, and potential liability. A wrong selection triggers unnecessary audits.
Appointing a Tax Representative
Many foreign nationals and non-resident directors underestimate the practical hurdles of SARS compliance. I have seen companies stall for months because no one in the country could sign a crucial return. Appointing a tax representative is not merely a formality during company registration SARS. It is a strategic safeguard. SARS requires a physical address and a human point of contact for audits and correspondence. Without a local representative, your compliance profile remains incomplete.
This individual acts as the official liaison. They receive all correspondence, submit documents, and manage the eFiling profile on your behalf. The representative does not need to be an accountant, but they must be a resident with a valid SARS eFiling profile. Your legal responsibility remains intact. You must still verify what is submitted. For a smooth process, your representative should handle:
1. Tax clearance certificate applications
2. VAT and PAYE submissions
3. Responses to SARS queries
4. Notice of assessments
A well-chosen representative bridges the distance between your boardroom and the tax authority. They keep your status active without unnecessary delays.
Understanding Tax Obligations
SARS does not warn you. One day you are trading, the next your bank account is frozen over a compliance gap you never saw coming. I have watched a Johannesburg based NPO lose its tax status because the founding director believed registration was a single event. It is not. It is the beginning of a relationship with a system that demands constant attention.
The preparation phase determines whether that relationship becomes a burden or a routine. Most applicants focus on the paperwork and overlook the operational reality. That is a mistake. When you begin company registration sars, you are not just filing forms. You are committing to a calendar of deadlines, returns, and payments that will follow you for the life of your entity. The obligations fall into three broad categories:
– VAT registration once your turnover exceeds R1 million
– PAYE for any employees on your payroll
– Income tax on your annual profits
Each obligation carries its own filing rhythm. VAT is bimonthly or monthly. PAYE is monthly without exception. Income tax is annual. You must map these dates before you register, not after. Your cash flow needs to absorb the tax liability from the first month of trading, not the first month of assessment. I have seen too many businesses treat the first year as a grace period. It is not. SARS expects provisional tax payments from your second year of operation, and those payments are based on estimates you make under penalty of interest for underestimation.
The real preparation is mental. You must accept that company registration sars is the starting line, not the finish. Your tax obligations will shift as your business grows. The systems you build now, the records you keep, the deadlines you track, these are the scaffolding that keeps your status alive. Without them, you are simply a name on a register waiting for an audit.
Step-by-Step Process to Register Your Company for SARS
Online Registration via eFiling
Once your company’s legal foundations are set, the next step unfolds online. The eFiling platform handles company registration sars digitally. I have guided many clients through this process.
To begin, follow these steps:
- Create an eFiling profile using your personal credentials.
- Link your company’s tax number to the profile.
- Submit the registration forms for each tax type.
- Await the notice of registration from SARS.
Each step demands precision. A single mismatch can stall the entire process. You can save progress and revisit the portal at your own pace.
The eFiling system sends notifications directly to your inbox. This keeps the entire registration process transparent from start to finish.
Completing the Necessary Forms
Completing the necessary forms for company registration sars demands precision. The eFiling portal presents each form sequentially, and every field carries weight. I have seen registrations stall over a single digit in a bank account number or a misspelled director’s name. Check each entry twice before moving forward.
The system allows you to save and return later, a blessing for busy business owners. Use this feature! Rushing invites errors that cost time later. The forms themselves are straightforward once you understand what each section asks. Your accountant or tax practitioner can review everything before you hit submit.
Once submitted, a waiting period follows. SARS will send a notice of registration to your eFiling inbox. That notification confirms your company registration sars is complete.
Verification and Approval Process
Most applications entering the SARS verification queue never encounter a human reviewer. The system runs automated checks that compare your submissions against the CIPC database, banking records, and previous tax histories. Discrepancies surface here. A single mismatched digit in your banking details triggers a manual review, and I have seen that extend approval timelines by weeks.
The approval process for company registration sars follows a defined path:
- SARS validates your taxpayer profile against CIPC records
- Bank account verification is performed electronically
- Your tax type selections are assessed for correctness
- The system links your new entity to your existing eFiling profile
Each step must clear before final approval for your company registration sars lands in your eFiling inbox. Some applications clear within three business days. Others take weeks. When verification stalls, SARS requests supporting documents through the portal, and the entire timeline resets. The eFiling inbox carries all communication throughout this period!
Receiving Your Tax Reference Number
The moment your verification clears, a number appears in your eFiling inbox. This is your company’s tax reference number, and it differs from your VAT or PAYE registration numbers, though many assume they are interchangeable. For company registration sars, the sequence follows a specific order:
- Access your eFiling profile and select the new entity
- Navigate to the ‘Tax Status’ section
- Locate the notice confirming your income tax number
- Save or print the confirmation for your records
The system generates this notice automatically after your tax types activate. Your appointed tax representative receives the same notification. I have watched clients wait for a physical letter that never arrives, assuming the system failed when the notice simply lived in the portal.
That number connects your bank account, your CIPC registration, and your entire tax history into one identifier. Without it, your company registration sars remains unfinished, and your first provisional return cannot be submitted.
Common Challenges and How to Overcome Them
Dealing with Delays
Delays shadow every step of the company registration sars journey. What should take days often stretches into weeks. The usual cause is incomplete documentation. A missing signature or a single unchecked field stops the entire process cold.
Other challenges trigger holds that consume days:
- Mismatched details between CIPC and SARS records
- Bank account verification failures
- Unpaid tax debts from previous entities
The people who move through quickly share a common habit. They verify every detail before submission, keep their eFiling profile active, and answer SARS queries within two days. Registrations proceed faster when preparation happens before pressing send.
Correcting Errors
Errors surface in strange places. A bank verification code that does not match, a director’s ID number transposed, a trade name that differs from the tax type selected. Each mistake follows a different correction path within company registration sars.
For entity details that CIPC holds, you must resolve mismatches with SARS first. SARS will not accept amendments until the two databases align. This is where many company registration sars processes stall! Banking details require a fresh letter from the bank. A note on letterhead does not pass verification.
The common correction steps include:
– Request a SARS COR17 form for registration amendments
– Attach supporting documents for each changed field
– Submit via eFiling under the “Manage SARS Correspondence” tab
Submitting a new registration to override an old one creates duplicate tax reference numbers. Those duplicates trigger penalties. The formal amendment route exists to prevent this outcome.
Maintaining Compliance
Maintaining compliance rarely ends with a successful company registration sars outcome. The real test arrives with the first filing season. Many owners discover that their tax type obligations shift as turnover grows, and failing to monitor those thresholds creates unexpected liabilities.
Keep a calendar of every submission date, not just for income tax. VAT periods arrive quarterly, and provisional payments sneak up twice a year. One missed deadline triggers penalties that compound quickly!
Common pitfalls we see repeatedly:
- Updated contact details that never reach SARS
- Bank account changes without a fresh confirmation letter
- Forgetting to deregister old tax types when business activities change
Your company registration sars paperwork is never truly finished. Treat compliance as a recurring appointment, not a one-time event.
Post-Registration Obligations
Filing Tax Returns
Once the reference number arrives, the true weight of your decision settles upon you. The South African Revenue Service expects a reckoning each year. Your tax return calls you back to account for what you have built and what you have lost within your company registration sars journey.
The filing cycle follows a grim and predictable schedule. Provisional taxpayers submit twice a year. Non-provisional entities face an annual filing. Miss these windows, and the penalties accumulate without mercy.
Consider what your return must contain:
- Statements of income and expenses
- Records of deductions claimed
- Supporting documentation for exemptions
The eFiling portal dominates this process. It stores your history, remembers your omissions, and waits for your next submission. Your company registration sars obligations do not end with approval. They merely shift shape.
Paying Provisional Tax
Provisional tax is not a tax on profits. It is an advance payment against what your company will owe at year end. The South African Revenue Service asks for two payments each financial year, one at six months and one at year end, and it expects you to estimate the amount honestly.
Your company registration sars process may have ended, but the cash flow commitment has only begun. Underestimating your taxable income triggers a penalty, not a gentle correction. The eFiling portal calculates your provisional liability from the figures you supply, and it remembers previous assessments when you submit.
- Estimate total taxable income for the current year
- Subtract allowable deductions and losses
- Apply the correct tax rate to the balance
That estimate becomes a binding obligation. I have seen too many directors treat it as a rough guess. The first payment lands six months into your financial year, and the second follows before the year closes.
Keeping Records
Each invoice issued after your company registration sars approval carries a hidden obligation. The South African Revenue Service expects you to preserve every financial record for five years. That includes source documents, bank statements, contracts, and correspondence with suppliers. No exceptions.
A practical filing system matters more than having a box of papers. SARS auditors reconstruct your taxable income from the evidence you provide. Missing records turn a clean assessment into a contested one. This means specific items:
- Cash sales slips
- Purchasing invoices
- Petty cash vouchers
- Bank reconciliations
Store these in a format you can retrieve quickly. The eFiling portal may request them digitally, and your response time affects the audit result. Company registration sars obligations do not end at approval; they live in every record you keep.
Managing Changes in Company Details
Once your company registration sars approval lands, the administrative burden continues. A change of address, a new director, or an altered business structure demands immediate attention. SARS does not chase you for these updates. They expect you to volunteer them through the eFiling portal. Waiting until the next tax season invites penalties and a shadow over your compliance record.
Keep a checklist near your financial files. When something changes, tick off the details that need updating:
- Registered postal and physical addresses
- Director and member particulars
- Banking details for refunds
- Registered business type or trade name
Each omission appears deliberate to an auditor. The system tolerates mistakes, but never silence. You own this obligation, and the window to correct it stays open only as long as you remain vigilant.
0 Comments